President Bola Tinubu says his administration is working to reverse Nigeria’s longstanding economic underperformance through reforms aimed at removing structural obstacles, stimulating productivity, creating jobs and promoting shared prosperity.
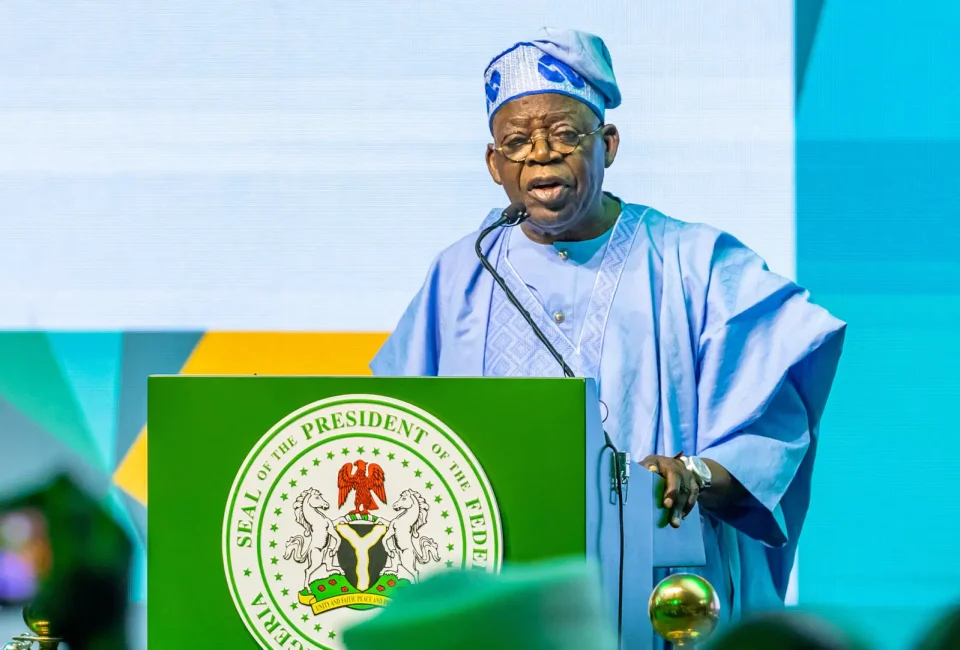
The President spoke through Vice President Kashim Shettima at the opening of the 32nd Nigerian Economic Summit Group (NESG) summit in Abuja on Monday. He said the administration began with difficult economic adjustments because sustainable growth could not be achieved through shortcuts.
Tinubu explained that the reforms were intended to improve livelihoods and expand opportunities for young job seekers, farmers, manufacturers, entrepreneurs and innovators.
He added that stabilising the economy was necessary to unlock the potential of Nigeria’s growing population and create an environment in which public and private sector investments could expand and generate employment.
The President said the summit’s theme, “Growth That Works: Delivering Jobs, Productivity and Shared Prosperity,” built on the previous edition’s ambition of achieving a prosperous and inclusive Nigeria by 2030.
According to him, the government has introduced measures to dismantle structural barriers, strengthen economic foundations, restore confidence and establish the conditions for sustainable growth.
Tinubu calls for better-quality jobs and higher productivity
While acknowledging progress under the reforms, Tinubu said job creation alone was insufficient. He stressed the need to improve the quality of employment, tackle underemployment and make better use of Nigeria’s underutilised workforce.
He maintained that infrastructure projects should be assessed by the economic activities they generate, while education should be measured by the skills and productivity it delivers. He also called for industrial policies that improve the competitiveness of local businesses and investment incentives that attract capital, technology, exports and jobs.
Citing figures from the National Bureau of Statistics (NBS), the President said Nigeria’s inflation-adjusted Gross Domestic Product grew by 3.89 per cent in the first quarter of 2026, compared with 3.13 per cent in the corresponding period of 2025.
He added that non-oil activities contributed 96.08 per cent of GDP, while manufacturing expanded by 3.29 per cent and the oil sector recorded growth of 2.57 per cent.
Tinubu also disclosed that capital importation reached $10.37 billion in the first quarter of 2026, representing an increase of 83.83 per cent compared with the same period in 2025. He said the figure covered both portfolio investments and foreign direct investment.
The administration, he added, would continue to simplify regulations, improve transparency, make policies more predictable and expand access to finance.
On taxation, the President said the reforms were designed to create a modern and equitable system capable of funding development while providing businesses with greater certainty.
He also highlighted ongoing efforts to reform the electricity market and attract investment across power generation, transmission, distribution and alternative energy.
In agriculture, Tinubu said the government was working to link farms with storage facilities, processing centres and markets while expanding irrigation, mechanisation, financing and rural infrastructure.
He added that the administration wanted to move the solid minerals sector beyond raw-material extraction towards domestic processing, industrial production and exports.
Despite the reported gains, the President acknowledged that much remained to be done. He also praised the ability of young Nigerians to compete internationally in technology, financial services and the creative industries.
Amina Mohammed urges government to consolidate reforms
United Nations Deputy Secretary-General Dr Amina Mohammed acknowledged the gains associated with the economic reforms but called for urgent efforts to consolidate and stabilise them.
She also stressed the importance of managing public expectations and commended the African Development Bank for its new development financing framework, particularly its emphasis on programmes expected to deliver significant development outcomes across Africa.
Meanwhile, the Minister of Finance and Coordinating Minister of the Economy, Dr Taiwo Oyedele, presented the proposed Nigerian Economic Policy Framework.
Oyedele described the framework as a national economic doctrine intended to guide government decision-making and establish how the country measures meaningful economic progress.
He invited the NESG and private-sector experts to scrutinise the draft using evidence and figures. He identified enterprise, open but fair markets and coordination across government as some of its guiding principles.
The proposed framework also prioritises economic stability, human capital development and productivity.
NESG chairman calls for economic stability
In his welcome address, NESG Chairman Olaniyi Yusuf said participation in the 32nd summit demonstrated stakeholders’ commitment to inclusive and impactful economic growth.
He acknowledged government efforts to improve the business environment but argued that the priority following the structural changes introduced by the Tinubu administration should be economic stabilisation rather than policy reversal.
BUA Group Chairman and Founder AbdulSamad Rabiu also commended the reforms, saying they had started addressing longstanding challenges facing Nigerian businesses.
Although he recognised the difficulties experienced by ordinary Nigerians, Rabiu said improved access to foreign exchange had created a more predictable business environment.
He recalled that businesses had previously struggled to obtain the foreign currency required to import raw materials and machinery, even when they had sufficient naira.
Those present at the summit’s opening included Anambra State Governor Professor Chukwuma Soludo, Lagos State Governor Babajide Sanwo-Olu, Minister of Budget and Economic Planning Senator Abubakar Bagudu, Minister of Industry, Trade and Investment Dr Jumoke Oduwole, Minister of Livestock Development Idi Mukhtar Maiha and Minister of State for Budget and Economic Planning Dr Doris Uzoka-Anite, alongside business leaders from Nigeria and other countries.
Source: Vanguard
